Sunday, August 28, 2022

A misconception about FIRE

So I was chatting with my wife who is not really an advocate of the FIRE lifestyle.

Her reasoning is as such:

There is no point saving up so much if you can't enjoy it in the end.

She cited the example of an uncle who suffered from dementia and died with $1 million in his bank account. It seems that this uncle worked hard his entire life but was not able to enjoy the fruits of his labour. He also has no offsprings who can inherit his wealth.

This story to me, is the perfect example why we need to pursue the FIRE lifestyle. With the FIRE lifestyle, one can retire much earlier e.g. 40, 45, 50, or 55 and enjoy the fruits of his labour. 

Undeterred, she raised another point. 

There is nothing much to enjoy about the FIRE lifestyle. You cannot eat at restaurants, you cannot travel, so what is the point even if you are able to achieve FIRE?

Do not be mistaken, actually FIRE does allow one to eat at restaurants and travel. But you have to build this into your budget, so it simply means you will need a bigger sum of money to achieve FIRE, which in turn means it will take longer for you to FIRE. There is nothing wrong with that, it is simply a matter of choice. Nobody is saying you have to FIRE by 40. The retirement age in Singapore is currently 63, you can FIRE at 62 if you want. Imagine! You have earned yourself an opportunity to retire and escape from your soul-sapping work one year earlier. Is this not a worthwhile pursuit in itself? Is this not worth fighting for?

In a span of a few days, CNA published another article about FIRE:

https://www.channelnewsasia.com/singapore/fire-movement-financial-independence-retire-early-2881076

From the article, here are some crtifcisms of FIRE:

Despite achieving FIRE, these individuals “found no satisfaction in their accumulated wealth”, suggesting that “frugality can diminish the joys of life greatly”, he noted.

You have to understand what your priorities are. If you plan to travel to far-flung places yearly, then probably FIRE is not for you. On the other hand, if you are fine with travelling to nearby countries, and yet have the time to pursue your passions, then FIRE is worth it.

“The most common criticism I get is that life is uncertain, and one should enjoy what money can do, while you still can,” he said. 

This is the typical YOLO mindset which got a lot of youngsters into trouble later on in life. There is uncertainty, but life is a game of probabilities. You have to plan for the scenario with the highest probability for you. For most, it is living to your 80s.  

“But what you cannot get back is time. What you are giving up to save the money … is hours with your children, with your friends, with yourself. If you are willing to give up that time, then I think it’s a perfectly sound decision. For most people, it depends on what their priorities are.” 

This is nonsense!  The whole purpose of FIRE is to allow yourself more time to pursue what you have always wanted to do.

What do you think? Let me know in the comments below. 

Tuesday, August 16, 2022

FIRE is going mainstream

You know FIRE is going mainstream when it appeared on the national news:

https://www.channelnewsasia.com/commentary/fire-financial-independence-retire-early-work-jobs-invest-2881331

Here's a summary of what FIRE is about in one paragraph:

Adherents of FIRE aim to save 70 per cent or more of their full-time income. The holy grail is to save 25 times of one’s annual expenses and make 4 per cent annual withdrawals for living expenditures.

The author tried to show both the pros and cons of FIRE:

When FIRE becomes the prism through which one views the world, decisions are rational only when they make financial sense. However, things that don’t make financial sense are enriching in many other ways.

And he gave some examples below this paragraph, such as planning an extravagant wedding to celebrate with friends, splurging on pumpkin-spiced latter while catching up with old friends, etc.  

The above does not really make sense if you think about it. If the intention is to celebrate with friends, you do not have to splurge on an extravagant wedding. Also, if you want to catch up with old friends, you can do so at the neighborhood kopitiam. 

Coincidentally there is another article about FI in the news. I think this gentleman summed it up best what's good about FI:

https://www.asiaone.com/singapore/inflation-what-inflation-asks-carsexpo-visitor-after-seeing-long-lines-car-show-travel

Asked whether inflation has affected him, Francis, 65, told Stomp: "I retired at 59 when I achieved financial independence because I married early to bring up my kids who are now independent. I started financial planning after national service, taking advantage of my long runway. I worked hard and saved. 
"Now I am enjoying the fruits of my labour and enjoying life with no worries. I don’t bother about inflation."


Saturday, July 30, 2022

Dividends for Jul 2022

 Here are my dividends for Jul 2022:


So I collected $685.91 in dividends for July 2022. 

In case you are wondering, some stocks are repeated because I have 2 brokerage accounts. 

Here are my monthly dividends over the last 4 years:


Can't wait for the bumper harvest of dividends coming up in Sep!

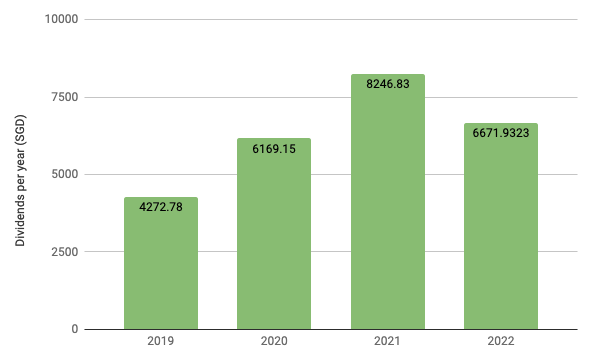
Here are the dividends I collected every year until the current day:


Saturday, July 23, 2022

This too shall pass - part 2

 It has been 2 months since my previous post about my portfolio taking a beating:

http://financeopti.blogspot.com/2022/05/this-too-shall-pass.html

I think it is time to re-evaluate the percentage gain(or loss) on my portfolio.

At this point in history, the Russia-Ukraine war is still ongoing with no signs of letting up. Covid-19 is causing lockdowns still in major Chinese cities. US-China tensions remain high. 

However, there are a couple of good news:

Somehow Russia-Ukraine managed to ink a deal to reopen grain exports, thereby alleviating the global food crisis:
https://www.straitstimes.com/world/europe/ukraine-russia-ink-deal-to-reopen-grain-export-ports

Petrol prices dropped to the lowest in 4 months:
https://www.straitstimes.com/singapore/transport/petrol-prices-fall-to-lowest-in-four-months-with-two-grades-below-3-a-litre

Here are the overall returns of the components in my portfolio:

Cryptocurrency -56.68%

SPY Fund          -7.23%

Bond                 -10.41%

USA                  -4.62%

One-Fourth       -7.39%

SGP                  +6.48%

BCIP                +3.03%

CPFIS              +17.89%

Dividends are not included in the above. 

Clearly, we are not out of the woods yet.

Thursday, July 14, 2022

Roboadvisor Returns - Are they Real?

 So this link came to my mailbox the other day:

https://blog.seedly.sg/robo-advisors-returns-revealed-endowus-syfe-kristal-ai-and-more/#syfe

Some of the claims seem too good to be true. For example, for Endowus below, most of their funds had positive returns:


It is the same for Syfe:


The good thing is that I have both Endowus and Syfe accounts, so I can verify whether their returns are as good as claimed. 

Firstly, for Endowus I have the Endowus Core Flagship (80/20) fund. I started with $9,999.91 in Feb 2021 and ended with $24,911.83 in Dec 2021. I contributed $1000 every month starting from Feb 2021 till Oct 2021, and then in Nov and Dec 2021, I contributed $2000 monthly. 

Another piece of information you need is that the tables above show time-weighted returns, which is equivalent to the compound annual growth rate (CAGR) or the 'rate' in the fv() formula in Excel and Google Sheets: https://support.google.com/docs/answer/3093224?hl=en

So now you have the start value of your fund, the end value, and the monthly installments you make to the fund, all you have to do is to adjust the 'rate' inside the fv() formula until the displayed value is the same as your actual end value ($24,911.83 in my case).

Here's what I found for Endowus:
Claimed returns from the table above:  17.91%
My actual returns:                                 13.10%

Hmm...a bit off but that could be because I didn't contribute for the month of Jan 2021.


Now let's do the same analysis for Syfe:

For Syfe I have the Core Equity 100 (100%) fund. I started with $2,028.28 in Jan 2021 and ended with $16,879.90 in Dec 2021. I contributed $1000 every month starting from Feb 2021 till Oct 2021, and then in Nov and Dec 2021, I contributed $2000 monthly. 

Here's what I found for Syfe:
Claimed returns from the table above:  16.04%
My actual returns:                                 10.50%

Hmm...again the actual returns are lower than what is claimed.


So what do you think? How did these roboadvisors compute their time-weight returns? My actual results seem quite off the mark. 

By the way, if you are interested in these Roboadvisors, feel free to use my referral codes:

Endowus:   HDOJH

Syfe:           SRPSL4GWK

Sunday, July 10, 2022

Side Hustle Earnings for May-Jun 2022

 Doing food delivery is getting more mundane as time passes.

Firstly the weather is the really hot meaning I break out in heat rash after 2-3 trips. 

Secondly, I have been to most of the popular restaurants/routes in my housing estate so most deliveries are not new to me.

Hope that I will feel motivated enough to continue doing this for months to come.

Below are my earnings for May-Jun 2022.


Saturday, July 2, 2022

Dividends for June 2022

 Here are my dividends for June 2022:


So I collected $1174.18 in dividends for June 2022. 

In case you are wondering, some stocks are repeated because I have 2 brokerage accounts. 

Here are my monthly dividends over the last 4 years:

Here are the dividends I collected every year until the current day: