Friday, May 12, 2023

Maximizing your Retirement Pot: How to purchase T-bills using CPF

OCBC recently allows the user to apply for T-bills using CPF on the OCBC website. 

In this article, I will show a step-by-step guide on how to do just that. 

Log in to your OCBC account, and select "Singapore Government Securities":


Click the 'Buy' button under TBills:


Enter the details below, agree to the T&Cs, and click the 'Preview' button at the bottom right:


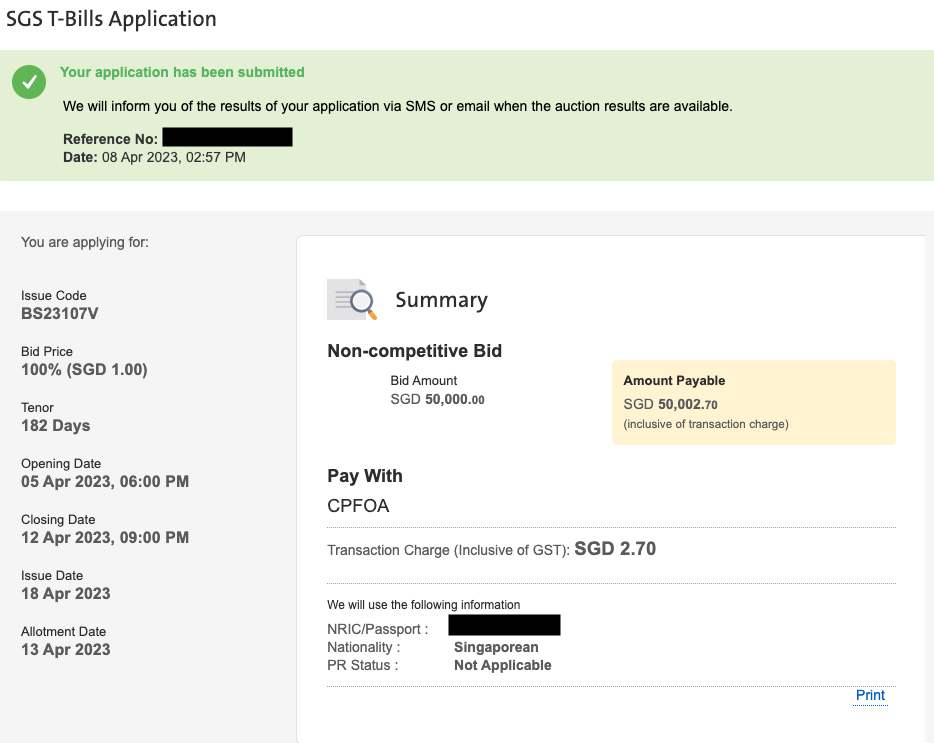
Once you submit the application, you will get a confirmation such as the one below:


Finally, on the issue date, you will get an email from OCBC that specifies the allotment amount, and deduction amount from your CPF.

Happy investing!

Friday, May 5, 2023

Dividends for Apr 2023 [Financial Independence]

Here are my dividends for Apr 2023:


So I collected $784.79 in dividends for Apr 2023. 

In case you are wondering, some stocks are repeated because I have 2 brokerage accounts. 

Here are my monthly dividends over the last 5 years:


Here are the dividends I collected every year until the current day:


Onwards!

Friday, April 21, 2023

My Pitiful Returns from my Investment Linked Policy after 17 Years

So I recently terminated my Investment Linked Policy (ILP), in order to provide $$$ during my upcoming sabbatical. 

This ILP was started 17 years ago when I was still a young man.

From time to time I recorded the surrender value and how much I paid thus far, in order to figure out the returns. The returns here are calculated using the fv() function in Google Sheet and is equivalent to CAGR or time-weighted rate of return. 

ILP returns

The maximum return was only 4% in 2018!!

What is more, during the Covid-19 recession of 2020 the returns were 0%.

The returns were disappointing, to say the least. Hence I decided to terminate the policy while the returns were still positive at 1.9%.

This is also taking into account that there is more and more talk of an upcoming recession in 2023, such as those below:

https://www.cnbc.com/video/2023/04/14/singapore-cant-avoid-a-recession-economist-says-.html

https://www.straitstimes.com/business/ceos-delay-and-halt-investments-expect-upcoming-recession-survey

I will also share something which I believe is a totally inadequate effort on Income's part. In the portal, they only shared the simple returns but not the time-weighted returns. This is totally inadequate. Folks not versed in finance will believe their returns are great from the below, which shows 20.98%. They will think: Oh! Better than bank returns! That is wonderful!

In actual fact, after taking into account compounding effects, the returns are merely 1.9%...


Also, I looked at the performance of the fund versus its benchmark:


It says 10-year returns are 7.21% since inception returns are 5.96%. Incredulous! No idea where these numbers come from. Likely it is before fees are deducted. I certainly didn't get these returns with my hard-earned money, I only got 1.9% after 17 years.


Saturday, April 15, 2023

Taking a Gap Year

This article popped up in my feed today:

https://www.businessinsider.com/what-its-like-to-career-break-gap-year-resume-gaps-2023-4

I think it is worth a read.

The author has always wanted to write a book. She tried doing it while she was working, but could not manage due to other commitments such as family, work, etc. She summed it up best in:

Unfortunately, I just couldn't find the discipline to also be a good writer. And so, I felt like I needed to not be working at my job anymore. 

Finally, she made her decision:

I decided to prioritize my family and my dream of writing, and I handed in my notice in December 2022. 

Three months into her gap year, she quipped:

The pace of my day is so much slower now, and the freedom of that is shocking. I hadn't realized how much tension I'd been holding in.

I feel this pretty much mirrors my situation as well, except I have more things I want to do than her. 

Sometimes once you have prepared all you can, you just have to take a leap of faith. 

Take risks, dream big. 

Friday, April 7, 2023

Dividends for Mar 2023 [Financial Independence]

  Here are my dividends for Mar 2022:


So I collected $1,465.60 in dividends for Mar 2023. 

In case you are wondering, some stocks are repeated because I have 2 brokerage accounts. 

Here are my monthly dividends over the last 5 years:


Here are the dividends I collected every year until the current day:


Onwards!

Friday, March 31, 2023

My Prediction of the S&P500 was 100% Accurate!

Around one month ago I drew the below chart in this post: http://financeopti.blogspot.com/2023/02/state-of-s-and-sti.html (note the hand-drawn arrow on the right):


It turned out that after one month the market moved exactly as in accordance with the arrow I drew above!


Since the S&P500 broke through the downtrend resistance, there should be more upside to come in the short term.

As for the STI, this is the chart from one month ago:


Here's what I said one month ago about the STI: 

It recently broke through the resistance level at 3302. Also, there is a bearish crossover of the 10 and 50 day simple moving average. Room for further fall, before a rebound. 
It turns out that is exactly what happened - the STI fell to around the 3100 level before re-bounding:


Good news is that the 10 day simply moving average just cut the 200 day simple moving average from below, which indicates a bit more upside in the next few days. 

Woohoo!

Saturday, March 25, 2023

Breaking Free: I have achieved FINANCIAL INDEPENDENCE 3.0!


I have achieved the FI 3.0 target I set for myself. Let me share my journey to get to this point:

I achieved FI (Financial Independence) 2.0 in Jun 2021.

I have been aiming for FI 3.0 since Dec 2021 (see this post: http://financeopti.blogspot.com/2021/12/revisiting-my-fi-fi30.html).

Firstly, a recap of what is FI 3.0. It has a few buffers baked in:

  • CPF is not included in the Starting Balance - this is the first buffer
  • The withdrawal rate is reduced from 4% to 3% - this is the second buffer
  • Certain expenses are assumed to last till perpetuity, even if it may not be the case. An example is children's class fees. 

Below is the amount I have accumulated up to now:


Which is more than the 'Required Savings' necessary for FI:


In other words, I have achieved FI 3.0!!

I have started this journey ever since I completed my graduate studies. Roughly, it took me 11 years to get to this point. 

I just want to share some practices that helped me get to this point:
  • I own only 1 property - my HDB flat, which is my matrimonial home
  • No car
  • I use freebies whenever possible - my watch is free, my shoes are free, and my bag and jacket are given free from my previous companies
  • For 2 years, I took MRT to work at unearthly hours (exit station before 7.45am) to spend $0 on transport
  • Side hustles - I took up side hustles including food delivery, paid surveys, writing 2 blogs (one technical blog and one FI blog)
  • I do repayments to my mortgage loan regularly - now my loan has only ~$950 remaining
  • I invest regularly - in stocks and bond
  • Whenever I get upset at work, I keep in mind I have a bigger goal in my life - to achieve FI and I endured it to get to this point
In hindsight, some points above actually didn't help much on my FI journey (paid surveys paid peanuts for example), but they helped build the discipline and the conviction I needed to achieve FI. No regrets.

What's next for me? Well, I plan to take a sabbatical (minimum 9 months) from my present company.

Here are some of my reasons for taking a sabbatical:
  • Be able to sleep better at night - e.g. for the past week I can't get to sleep until after midnight, or very often I wake up 2-3am, think about work, and then am not able to get back to sleep
  • I burst the income ceiling for BTO long ago - by taking a sabbatical, I will draw no CPF, which will qualify me for our dream 5-room BTO
  • Issues at work - unsupportive and unhelpful colleagues that only care about themselves, not enough support from bosses, too many whiners and complainers at work thus creating a toxic environment, etc. Typical work gripes I guess
  • Real-life test of my FI expenses - all my expense calculations to date are based on when I am still working full-time. Will my expenses stay the same after I stop working full-time? Only by stopping full-time work will I know for sure
  • Find time to work on my technical blog
  • Find time to create more quality articles for my FI blog (yes, this blog)
  • Find time to spend more quality time with my kids e.g. if my kid is sick, he can stay at home instead of going to my parent's place, or I can avoid a scenario whereby I have to juggle taking care of him and working at the same time
  • Find time to do some self-study
  • Find time to rest more - I got too many comments from colleagues and family that I look tired over the past few years. I want to do something about it by finding time to get proper rest and doing something that I am truly passionate about
  • Find time to start exercising more regularly instead of just once a week - need to take care of my health. Now in my 40s, health issues are starting to pop up: eyesight not good, catch bugs easily, knee pain, etc. 
  • Find time to have the freedom to travel a bit further to get a good lunch instead of eating the same stuff around my neighborhood because I have to get back to work 
  • Find time to do volunteer work and help the community - I find this to be meaningful
  • Find time to be closer to nature - will like to go for regular nature walks and not have to take leave to do so
  • Find time to do some administrative things - writing my will, fixing my laptop, and changing to a cheaper phone plan are some of them
  • Find time to launch my startup. Yes! I have many ideas! Now that I am FI, coupled with my work experience over the past few years, there is no better time to start!

Do you have any questions for me? Ask below!